
By MyAutoResource Editorial Team · Reviewed by Steven Sun · 6 min read · Updated September 14, 2026
- A single at-fault claim can raise your premium 10 to 20 percent, and multiple claims in a short window can push that higher, on top of a car payment that does not change.
- California’s insurance regulator confirms insurers can surcharge a driver found at least 51 percent at fault, while a not-at-fault claim is not supposed to trigger that increase.
- Most claims stay on your record three to five years, so a single bad year can affect your total monthly car cost well past the year it happened.
- Your loan payment is fixed for the life of the loan. Your insurance premium is not, which makes claim history one of the few levers that can still move your total cost of ownership after you have already signed for the car.
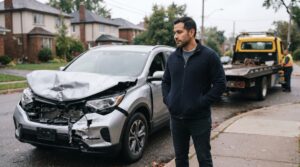
Daniel financed a used Corolla with a $412 monthly payment and a clean driving record. Six months in, another driver clipped his bumper in a parking lot and he filed a small claim to cover the $1,100 repair. At his next renewal, his premium jumped 18%, and that increase landed on top of a loan payment that was never going to change. The claim did not touch his financing. It touched the other half of what it actually costs to keep driving the car he is still paying off.
What Counts as Claim History
Claim history includes every incident reported to your insurer. This typically covers:
- Collision claims
- Comprehensive claims such as theft, fire, or weather damage
- Liability claims involving damage to others
- Medical claims related to accidents
Even if no payout was made, the report itself may still appear in your record. Some insurers track zero-payout claims as part of their internal risk modeling.
Why Insurers Care About Past Claims
Insurance is built on prediction. Providers estimate how much risk you carry and adjust your premium accordingly. A clean record suggests low risk. A history of frequent or costly claims suggests higher risk.
Insurers do not just count the number of claims. They look at behavioral patterns. For example:
- Several small claims in a short period may suggest carelessness
- A single large claim may reflect bad luck, but it still affects your score
- Fault-based claims carry more weight than no-fault incidents. California’s own insurance regulator spells this out: if you are found at least 51 percent at fault for an accident, your insurer can raise your premium at renewal through what regulators call a surcharge, while an accident that is not your fault is not supposed to trigger that increase
These patterns help insurers decide how to price your coverage and which risk tier to assign.
How Claim History Impacts Premiums
The impact varies by provider, but common outcomes include:
- Higher base premiums
- Removal of safe driver or loyalty discounts
- Reassignment to a higher-risk category
- Limited access to certain coverage options
In some cases, a single claim can increase your premium by 10 to 20 percent. Multiple claims may push that even higher, especially if they occur within a short timeframe.
How Long Claims Stay on Your Record
Most claims remain on your record for three to five years. The exact duration depends on the insurer and the type of claim. Some states also regulate how long claims can be used in pricing decisions.
Once that period ends, the claim may no longer affect your premium. Until then, it remains part of your risk profile.
What You Can Do to Minimize Impact
You cannot erase past claims, but you can manage how they affect your future. Consider these strategies:
- Avoid filing small claims. If the damage is minor and repair costs are manageable, paying out of pocket may be smarter.
- Ask about accident forgiveness. Some insurers offer this feature to protect your rate after your first claim.
- Bundle policies. Combining auto and home insurance may unlock discounts that offset premium increases.
- Shop around. Different insurers weigh claim history differently. A fresh quote may offer better terms.
- Improve your driving habits. Safe behavior reduces the chance of future claims and may qualify you for usage-based discounts.
These steps help you control your costs and rebuild your profile over time.
Why Timing Matters
The timing of your claims affects how insurers interpret your risk. Two claims in one year carry more weight than two claims spread over five years. Spacing matters.
If you are considering switching providers, check how your current claim history will be treated. Some insurers offer leniency for older claims. Others apply strict penalties regardless of age.
What to Watch for in Your Policy
Review your declarations page and renewal notices carefully. Look for:
- Changes in premium
- Removal of discounts
- Notes about tier reassignment
If you notice unexplained increases, ask your insurer for a breakdown. They should be able to explain how your claim history influenced the new rate.
If you are still financing the vehicle, treat that breakdown as part of your loan math, not a separate bill. A claim-driven premium increase does not show up on your loan statement, but it comes out of the same monthly budget as your car payment. Two drivers with an identical loan on an identical car can end up with meaningfully different total monthly costs once one of them has a claim on record and the other does not, even though neither one’s financing terms ever changed.
Claim history plays a central role in how insurers assess your risk level and calculate your premiums. It influences the discounts you’re eligible for, the coverage you’re offered, and the pricing tier you’re placed in. For anyone still paying off the vehicle, that record is worth tracking with the same attention as the loan balance itself, since it is the part of your total car cost still capable of moving.